Inventory vs. Books: Why Physical Stock Discrepancies Are a Major Financial Risk
Financial Controls
Inventory Governance
UAE Business Model
Treating physical counts as a warehouse chore rather than a vital financial control is a dangerous miscalculation. Your closing stock directly drives your COGS, balance sheet, and Corporate Tax position.
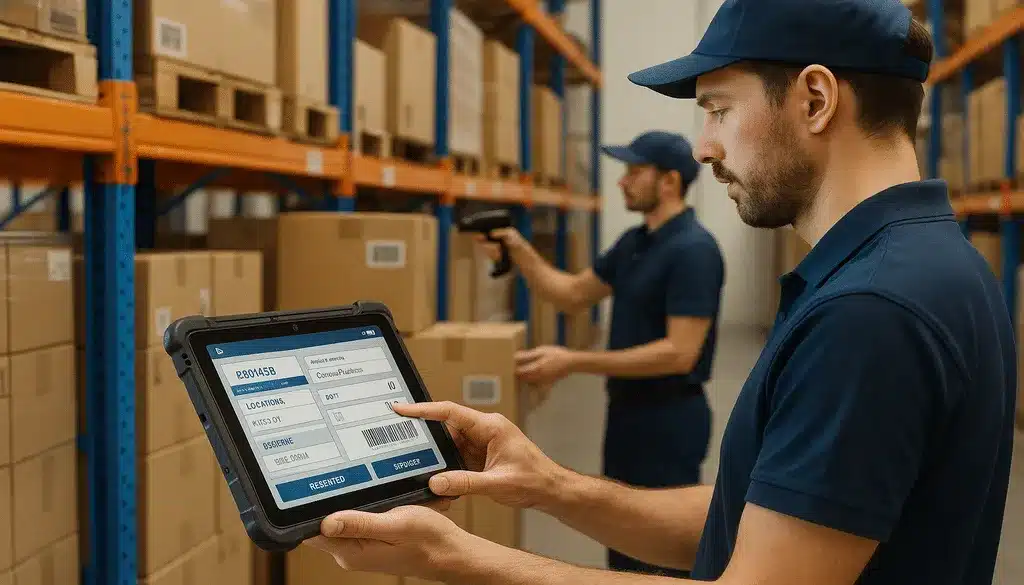
Your ERP system shows 100 units in stock. You walk into the warehouse and find 94. Or perhaps 108.
These mismatches between physical inventory and system records are among the most common recurring issues identified during inventory reviews.
Items may be recorded in the ledger but missing from the warehouse. Stock may be physically present but never entered into the system. Goods marked as “in transit” may already be sitting in the receiving area.
Too often, these differences are treated as minor warehouse housekeeping issues and resolved through a quick adjustment entry.
They are not.
Inventory is a critical financial asset. Its accuracy directly affects your balance sheet, Cost of Goods Sold (COGS), profitability, and Corporate Tax position.
The Hidden Financial Impact of Inventory Discrepancies
When physical stock differs from accounting records, the impact extends beyond warehouse operations.
Distorted Cost of Goods Sold
COGS is directly influenced by opening inventory, purchases, and closing inventory. If closing stock is overstated or understated, gross profit and financial reporting can also be distorted.Corporate Tax Exposure
Under the UAE Corporate Tax framework, taxable income is determined from financial results prepared using applicable accounting standards. An inaccurate inventory figure can therefore contribute to an incorrect profit calculation and tax position.Working Capital Inefficiencies
Inaccurate inventory records can create ghost stock, unnecessary purchases, delayed replenishment, dead inventory, and unexpected write-offs. Over time, these issues can quietly reduce working capital efficiency.Three Practical Controls
Inventory accuracy does not necessarily require a major operational overhaul. It requires disciplined verification and clear ownership.
1. Enforce Regular Cycle Counts
Do not rely solely on a stressful year-end physical stocktake.
Implement scheduled cycle counts throughout the year, prioritizing high-value, high-volume, or fast-moving inventory. Regular verification allows discrepancies to be identified while they are still manageable.2. Investigate Every Material Discrepancy
When physical stock does not match the system, avoid simply posting an adjustment.
Investigate the underlying cause. The difference may result from an unrecorded goods receipt, incorrect issue, stock movement error, shrinkage, or processing mistake.
The objective is not just to correct the number but to understand why the number was wrong.3. Align Warehouse and Finance Ownership
Inventory accuracy should not belong exclusively to the warehouse team or finance team.
Material inventory adjustments should require appropriate review and authorization, with warehouse and finance responsibilities clearly defined. Every significant adjustment should leave a documented audit trail.The UAE Context: Accurate Books in the Tax Era
The UAE’s fast-moving commercial environment has historically depended on efficient trade, logistics, and inventory turnover.
As businesses operate within a more formalized environment involving Corporate Tax, VAT, financial reporting, and stronger governance expectations, the quality of underlying financial records becomes increasingly important.
Physical inventory verification provides evidence that the figures appearing in the financial statements are supported by the assets actually held by the business.
Good governance does not mean slowing down warehouse operations with unnecessary bureaucracy. It means creating enough discipline to ensure that operational records and financial records tell the same story.
Final Takeaway
Your system says 100 units. The shelf says 94.
That variance should trigger a question, not an automatic adjustment.
Inventory counts are not simply a warehouse responsibility. They are a fundamental financial control that supports reliable financial statements, accurate profitability reporting, and a defensible tax position.
Verify the stock. Reconcile the books. Protect the accuracy of your financial position.
Frequently Asked Questions
Why are inventory discrepancies considered a financial risk rather than a warehouse issue?
Inventory feeds directly into the balance sheet and the calculation of Cost of Goods Sold (COGS). If physical stock does not match accounting records, your profit figures are distorted, directly impacting financial statements and corporate tax computations.
How often should UAE businesses conduct physical inventory counts?
While an annual year-end count is standard, growing businesses should implement regular cycle counts—counting subsets of inventory weekly or monthly—to catch discrepancies early and maintain ongoing ledger accuracy.
What causes the common gaps between ERP inventory and physical stock?
Common causes include unrecorded shipments, delayed goods-received notes, undocumented write-offs, shrinkage, data entry errors, and goods marked as in transit that have already arrived on the warehouse floor.
How do inventory errors affect UAE Corporate Tax compliance?
Corporate Tax calculations rely on net profit derived from financial statements. Inaccurate inventory valuation misstates COGS and gross profit, leading to incorrect taxable income reporting and potential penalties during an FTA audit.